Home Blog

OSC Enforcement: Ontario Securities Commission Coordinates Operation Niagara to Disrupt Crypto-Enabled Fraud

0

By Jean-Francois Amyot

Standfirst: The Ontario Securities Commission is coordinating and hosting Operation Niagara, a cross-agency initiative of law enforcement, regulators and private companies from Canada and the United States that begins November 16, 2026, to disrupt online crypto-fraud schemes, identify victims and connect them with support. The release announces an operation, not charges or findings against a named respondent.

What the OSC announced

In a news release dated November 16, 2026, the Ontario Securities Commission (OSC) announced that it is coordinating and hosting Operation Niagara, a cross-agency initiative bringing together law enforcement, regulatory agencies and private companies from Canada and the United States to disrupt online crypto-fraud schemes.

According to the release, beginning November 16, 2026, Operation Niagara will also identify victims to prevent further harm and connect them with support and assistance. The OSC said investigators, securities specialists and financial crime experts are using advanced technology and enhanced capabilities to disrupt organized fraud networks and identify victims in near real-time.

How the OSC described the operation

The OSC said Operation Niagara builds on previous exercises and uses enhanced techniques to detect a broader range of phishing attacks used to obtain access to cryptocurrency accounts. That includes instances where stolen access has not yet been exploited, creating opportunities for early intervention, according to the release.

The OSC also said the operation will use new ways of working to speed up intelligence collection and cross-border coordination, with enhanced technology allowing regulators and law enforcement to find where the fraud is taking place.

Bonnie Lysyk, Executive Vice-President, Enforcement, at the OSC, said in the release: “Fraud knows no border, and it targets everyday people.”

Who is taking part

The OSC thanked the Ontario Provincial Police (OPP), the Royal Canadian Mounted Police (RCMP), the United States Secret Service (USSS), and securities regulatory authorities across Canada, including the Alberta Securities Commission (ASC), the British Columbia Securities Commission, and the Autorité des marchés financiers (AMF). The OSC said the operation also benefits from the expertise and cooperation of private-sector partners.

Notes to editors in the release listed participating law enforcement agencies including Toronto Police, Sûreté du Québec (SQ), Quebec City Police, Calgary Police and Edmonton Police, and private-sector partners including Chainalysis, TRM Labs, Breadcrumbs, Elliptic, Collisionless and Addressable.

Background given in the release

According to the OSC’s notes to editors, Operation Niagara builds on a series of international cryptocurrency fraud-disruption initiatives that began with Project Atlas in 2024, followed by Operation Avalanche in 2025 and Operation Atlantic in 2026.

The release described cryptocurrency investment fraud as often relying on social engineering tactics to gain a victim’s trust, and approval phishing schemes that trick victims into granting access to their cryptocurrency wallets through what appears to be a legitimate request from a trusted service, allowing fraudsters to transfer assets that are often difficult or impossible to recover.

Status and what the release does not announce

Operation Niagara is an enforcement and disruption initiative announced as beginning November 16, 2026. The November 16, 2026 release does not name a respondent, does not announce charges, a proceeding, a settlement, a finding, an order or a sanction against any person or company, and does not report an outcome for any individual case.

Source: Ontario Securities Commission, “OSC coordinates Operation Niagara agencies to disrupt crypto-enabled fraud” — https://www.osc.ca/en/news-events/news/osc-coordinates-operation-niagara-agencies-disrupt-crypto-enabled-fraud

Announcement date: November 16, 2026

Jean-Francois Amyot is an independent journalist and author of The Art of War Remastered.

Paper First: Term Sheets, Subscription Documents and Why a Handshake Is Not a Closing

0

By Jean-Francois Amyot

Standfirst: A raise is not closed when someone says yes, and it is not closed when money lands in a bank account. It is closed when the documents say who bought what, on what terms, under which exemption, and when — and when the company’s own record matches those documents exactly. Paper first is not bureaucracy. It is the closing itself.

A yes is not a purchase

Every founder knows the moment: an investor listens, nods, and says, “I’m in.” It feels like the end of the hard part. Legally, almost nothing has happened yet.

No security has been described with precision. No price, class, or rights have been fixed. No investor qualification has been recorded. No one has acknowledged the risks, the resale restrictions, or the fact that the investment could be lost. And no record exists that a later investor, auditor, buyer, or regulator could test.

That gap between a verbal yes and a documented purchase is where many small-company problems are born. Months later the founder remembers a friendly conversation. The investor remembers a promise. The documents — if there are any — remember something else. When memories differ, the paper is what gets read.

The term sheet: a map, not the territory

The first document in most raises is the term sheet. Its job is to set out the main commercial terms in one place before longer documents are drafted: what kind of security is being offered, how much is being raised, the price or the way the price will be set, what rights the security carries, and any major conditions the parties expect.

Founders should understand two things about a term sheet. First, it is a negotiating map, not a substitute for the final documents. The details that protect both sides — definitions, conditions, representations, and what happens in specific events — live in the documents that follow, and a short summary can hide a long consequence.

Second, not every line in a term sheet carries the same weight. Some provisions are commonly treated as binding even in an otherwise non-binding summary — confidentiality is a familiar example — while the main investment terms are usually not final until the definitive documents are signed. Which parts bind, and which do not, should be stated on the face of the term sheet itself, not assumed from habit. If a founder cannot say which parts are binding, counsel should answer that question before anyone signs.

Read a term sheet for what will be hard to change later. Valuation is the number people notice. The rights attached to the security, how future rounds may dilute earlier investors, and what consent rights investors receive are the terms people live with.

The subscription documents: where the investor actually buys

If the term sheet is the map, the subscription documents are the purchase. In a typical private offering, an investor signs subscription documents that identify the investor, state the amount and the security being bought, and record the basis on which the investor qualifies for the exemption being used.

That last point is not a formality. Earlier articles in this series explained that an offering’s route depends on who is allowed to invest. The subscription package is where that planning becomes evidence. It is where an investor confirms accredited status where that status is required, acknowledges that the securities are restricted where they are, and confirms that they received the disclosure the offering promised to provide.

Subscription documents also protect the investor. They should make plain what is being bought, what it costs, what rights it does and does not carry, and how and when the purchase becomes final. An investor who is asked to wire money before seeing those terms is not being offered efficiency. They are being asked to buy first and read later.

Companies do not have to accept every subscription. A properly run offering reserves the ability to reject or reduce a subscription — for example, if qualification cannot be established, if accepting it would break the conditions of the exemption, or if the offering is oversubscribed. That right, and how refunds are handled if a subscription is not accepted, belong in the documents before money moves.

Disclosure must match the documents

Paper first also means consistency. The pitch deck, the term sheet, the subscription documents, and any filing made for the offering must tell the same story about the company, the security, the use of proceeds, and the risks.

Where they differ, the difference becomes the story. A deck that describes a use of proceeds the offering documents do not mention, a term sheet that promises rights the final documents narrow, or a social media post that states a return the documents carefully do not promise — each one creates a record that anti-fraud rules will be applied to. Exempt offerings are not exempt from honesty. A statement does not become safe because the offering was private.

This is why experienced founders freeze a single version of the facts before an offering opens, and then make every later document follow it. Updating disclosure when something material changes is not a weakness. Leaving three inconsistent versions in circulation is.

The cap table: the company’s memory

After the subscription documents, the next record is the capitalisation table — the cap table. It lists who owns what: every share issued, every option or warrant outstanding, and every convertible instrument that could become shares later.

A clean cap table is a closing document, not a housekeeping chore for next year. It should be updated as part of the closing itself, so that the day the money arrives, the company’s own record of ownership is complete. Founders who postpone that update discover the cost at the worst moment: in diligence for the next round, a sale, or a dispute, when promises made in emails and side conversations have to be reconciled with a register that was never kept current.

Three habits keep a cap table trustworthy. Record every promise when it is made, not when it is exercised. Keep the signed documents with the table, so every line can be traced to its source. And never let a side letter, a verbal discount, or an informal promise to an adviser live outside the record. If it affects ownership, it belongs on the table.

Money, closing, and the filing that follows

A disciplined closing fixes the mechanics in advance: where funds are sent, whether they are held until a minimum amount or another condition is met where the route requires it, when a subscription is accepted, and when the investor is actually recorded as a holder. “We received the wire” is not the same event as “the purchase closed,” and the documents should say which event does what.

Some routes add a notice filing after sales begin. Under Regulation D, for example, the U.S. Securities and Exchange Commission requires an issuer to file a Form D notice within 15 days after the first sale of securities in the offering — and the SEC defines that first sale as the date the first investor is irrevocably contractually committed to invest. Form D is a notice, not an approval, and it does not register the offering. But its deadline is counted from a documented event, which is one more reason the subscription date has to be precise rather than remembered.

Resale limits belong in this conversation too. Securities sold in many private placements are restricted securities, and investors should be told, in the documents they sign, that resale may be limited for a period and may require registration or another exemption. Learning that after purchase is a grievance. Reading it before purchase is disclosure.

What investors should ask before they sign

Paper first cuts both ways. Before signing, an investor can reasonably ask for the final or near-final documents, not only a deck; for a clear statement of the rights of the security being bought; for the current cap table or a summary of what will be outstanding after the round; for how their qualification will be recorded; and for what happens to their funds if the offering does not reach its stated minimum or their subscription is not accepted.

A company that answers those questions calmly, in writing, is showing how it will behave after the money arrives. A company that treats documents as an insult to trust is asking for trust on the one subject where trust should be verified.

The handshake still matters — as the start

None of this is an argument against relationships. Most early investment begins with people who believe in a founder, and that belief is real capital. The argument is about order. A handshake is an excellent way to begin a raise. It is a poor way to record one.

Shake hands, then do the paper — term sheet that states what binds and what does not, subscription documents that record who bought what and on what basis, disclosure that matches across every version, a cap table updated at closing, and any notice filing counted from the documented first sale. Founders who work that way are not slower. They are the ones whose next raise starts with records a new investor can trust, instead of apologies for records no one kept.

This article is education, not legal or investment advice. The documents a particular offering requires, and the terms they should contain, turn on the exemption relied on, the jurisdictions involved, and the company’s specific facts. Founders and investors should confirm their position with qualified securities counsel before any sale.

Jean-Francois Amyot is an independent journalist and author of The Art of War Remastered.
Accredited or Not? Who Is Allowed to Invest, and Why It Changes Everything

0
Accredited or Not? Who Is Allowed to Invest, and Why It Changes Everything

Before a founder can choose how to raise money, one question decides who may even be in the room: is each investor accredited? The answer determines which exemption is available, whether the offering may be advertised, what must be disclosed, and how an investor’s status must be checked — and it has to be answered before the conversation, not after the money arrives.

There is no certificate, and no government stamp

The first surprise for many founders is that “accredited investor” is not a licence anyone issues. No regulator examines an investor, awards a credential, and enters a name on a public list. Under the U.S. Securities and Exchange Commission (SEC) definition, an investor either meets one of the specified criteria at the time of the sale, or does not. The responsibility for making that determination — carefully, and on evidence appropriate to the offering — sits with the company selling the securities.

That makes accredited status a legal test, not a social description. A successful founder, a wealthy-looking neighbour, or a retired executive may or may not meet it. A younger investor who holds the right professional licence may meet it without meeting any wealth test at all. Assumptions based on lifestyle, job title, or confidence are not a determination, and in a later dispute or examination they will not be treated as one.

The individual tests: wealth, income, and professional knowledge

For individuals, the SEC groups the routes to accredited status in three broad families.

The financial criteria are the best known. An individual may qualify with a net worth over $1 million, excluding the primary residence, counted individually or together with a spouse or partner. Or an individual may qualify on income: income over $200,000 individually, or over $300,000 together with a spouse or partner, in each of the prior two years, with a reasonable expectation of reaching the same level in the current year. Note the discipline built into both tests. Net worth is not everything a person owns — the home they live in is taken out of the calculation. Income is not one good year — it must be shown for each of the two prior years, with a reasonable expectation for the present one.

The professional criteria recognise that financial sophistication does not only come from wealth. Investment professionals in good standing who hold the general securities representative licence (Series 7), the investment adviser representative licence (Series 65), or the private securities offerings representative licence (Series 82) may qualify. So may directors, executive officers, or general partners of the company selling the securities. Two narrower routes also exist: a “family client” of a qualifying family office, and, for an investment in a private fund, a “knowledgeable employee” of that fund.

Entities have their own routes. Depending on structure and assets, an entity may qualify if it owns investments in excess of $5 million, if it is one of the listed kinds of entity with assets in excess of $5 million, if all of its equity owners are themselves accredited investors, or if it falls within the categories for registered investment advisers, SEC-registered broker-dealers, and specified financial institutions. An entity formed simply to get around the test is a problem counsel needs to examine, not a workaround a founder should improvise.

Other jurisdictions draw this line in their own way, with their own definitions and thresholds. A raise that touches Canada, for example, is governed province by province — in Quebec by the Autorité des marchés financiers (AMF) and in Ontario by the Ontario Securities Commission — and a U.S. determination does not travel across the border. Founders raising in more than one country need the test applied, separately, under each system that applies.

Why one investor’s status changes the whole offering

Accredited status matters because exemptions are built around it. Change who is allowed to invest, and the structure, communications, and paperwork of the raise change with it. Regulation D’s Rule 506 — the route behind many U.S. private placements, which the SEC notes can be used to raise an unlimited amount — shows the trade clearly, in its two forms.

Under Rule 506(b), a company may sell to an unlimited number of accredited investors and to up to 35 other purchasers. Those non-accredited purchasers must be sophisticated — alone, or together with a purchaser representative, they must have sufficient knowledge and experience in financial and business matters to evaluate the merits and risks of the investment. In exchange for that limited room for non-accredited buyers, the company gives up reach: it cannot use general solicitation or advertising to market the securities. Including non-accredited investors also raises the disclosure burden, because they must be given disclosure documents generally of the kind used in Regulation A or registered offerings, including financial statements that in some cases must be certified or audited — and any information given to accredited investors must also be made available to them.

Under Rule 506(c), the bargain reverses. A company may broadly solicit and generally advertise the offering — but every investor in the offering must be accredited, with no room for the 35 non-accredited purchasers allowed under Rule 506(b), and the company must take reasonable steps to verify that status. The SEC describes verification as potentially including reviewing documentation such as W-2s, tax returns, bank and brokerage statements, and credit reports. A founder who wants to advertise a raise publicly has therefore chosen, at the same moment, a narrower investor pool and a heavier checking obligation.

The public-facing exemptions tell the same story from the other direction. Regulation Crowdfunding and Regulation A exist precisely to let companies reach investors who are not accredited — and, in return, they impose their own issuer limits, investor limits, intermediary or filing requirements, and ongoing obligations. There is no route in which a company gets a public audience, unlimited non-accredited participation, and light obligations at the same time. Accredited status is the hinge on which that trade turns.

A simple decision tree founders can use before any conversation

First, list who will actually be approached — not who might be interested one day, but the real people, in the real jurisdictions, for this raise. Second, test each person or entity against the definition that applies to them, and record how the test was met. Third, let the answers choose the route: an all-accredited, verified pool points one way; a pool that includes even a small number of non-accredited investors points another, and may rule out advertising the offering altogether. Fourth, set the communications to match the route before anything is posted, pitched publicly, or forwarded — because a message sent to the wrong audience cannot be unsent when counsel reviews it later.

Two cautions belong on the same page. Accredited does not mean an investment is suitable, safe, or likely to succeed; it is a threshold about financial capacity and sophistication, not a judgement about a particular deal. And accredited status does not dilute the anti-fraud rules, which apply to what is said to every investor, accredited or not. Securities bought under Rule 506 are also restricted securities, which under the SEC’s summary cannot be sold for at least six months or a year without registration — a limit investors should understand before they buy, not discover when they want to exit.

The question that protects both sides

Founders sometimes treat the accredited question as gatekeeping, and investors sometimes treat being asked as an insult. It is neither. It is the mechanism by which the law decides how much protective process a particular offering must carry. Asked early, it is a five-minute planning question that keeps a raise inside an exemption that actually fits. Asked late — after advertising has gone out, after a non-accredited friend has wired money into an accredited-only offering, after documents have been signed that describe a different pool — it becomes the question on which the exemption, and sometimes the investors’ right to unwind the purchase, depends.

So ask it first, ask it in writing, and ask it of everyone. Who is allowed to invest is not a detail of a lawful raise. In large part, it is the raise.

This article is education, not legal or investment advice. Whether a particular investor is accredited, and which exemption fits a particular offering, turn on the investor’s and the company’s specific facts and on the rules in force when the offering is made. Founders and investors should confirm their position with qualified securities counsel before any sale.

Jean-Francois Amyot is an independent journalist and author of The Art of War Remastered.
Lionel Richie at the Encore: A Great Evening, All Night Long

0
Lionel Richie at the Encore: A Great Evening, All Night Long
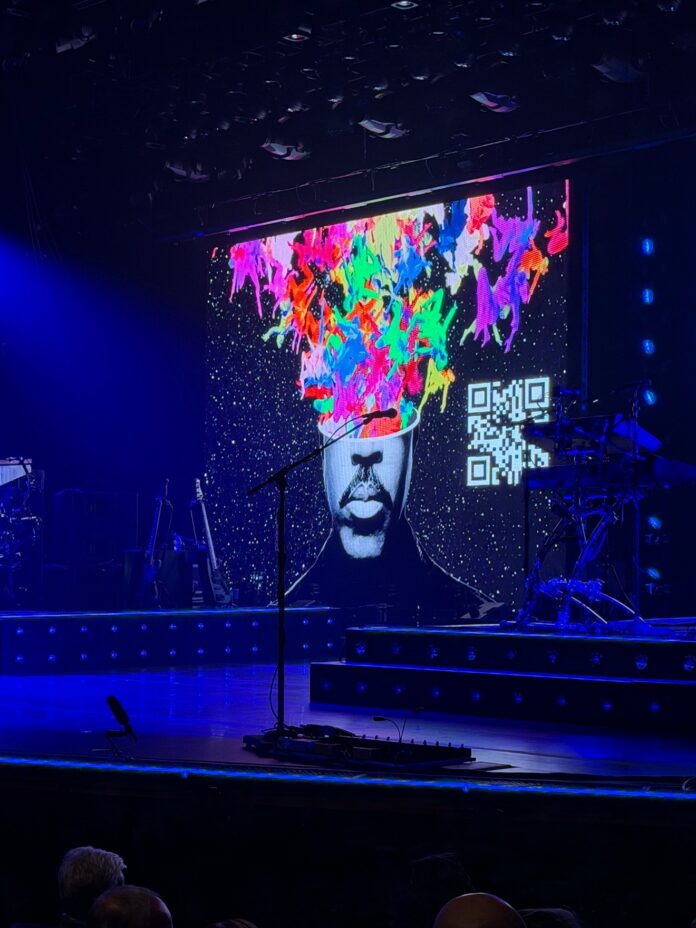
The Encore Theater stage before the show, photographed by the author from his seat — Orchestra Right, Row H.

There is a particular kind of performer who walks on stage and owns the room before the first note is finished. On Friday night at the Encore Theater, Lionel Richie reminded a sold-out room — my wife Julie and I among them, Orchestra Right, Row H — that he is very much that kind of performer.

Funny, energetic, and in complete command of the crowd

What struck me first was not the singing. It was the comedy. Richie is genuinely funny — relaxed, quick, and clearly enjoying himself as much as anyone in the seats. Within minutes he had the whole theatre with him, and he kept it there all evening, working the crowd the way performers of his generation learned to do it: no shortcuts, just presence.

One of his running bits landed perfectly. People keep acting, he said, as though he had been away somewhere — as if Lionel Richie had vanished for a few decades and only just come back. His answer, delivered with a grin, amounted to: away where, exactly? He has been here the whole time. The crowd loved it, and he is right. The catalogue never left, even if the spotlight wandered.

From the Commodores to the newest hits

The set ran the full arc of the career — back to his early days with the Commodores, through the great solo years, and up to his most recent hits. It is a remarkable thing to hear in one evening: songs that were on the radio when many of us were young, sitting comfortably beside the newer material, with the audience singing along to both.

Two moments stood out. The first was a duet performed with Kenny Rogers appearing on screen, from a previous performance — a pre-recorded partner, a live band, and a theatre full of people completely inside the song. It could have felt like a gimmick. It felt like a tribute.

The second was “Three Times a Lady” at the piano. No spectacle, no production tricks — just Richie, the keys, and one of the great ballads of its era, played the way it was written. It was also, I will admit, the song I sent Julie a link to when I first told her these tickets were booked. Hearing it live, next to her, was the evening’s high point.

One complaint — and it is a small one

If I have a single negative note, it is the sound. It was not perfect — a little muddy in places, the vocals not always as clear as they should have been. My guess is that the room itself is the reason: the Encore Theater is a small, intimate theatre, and a full band at full energy is a lot for a room that size to carry cleanly.

And the band deserves saying plainly: they were great. Tight, powerful, and clearly having fun — the sound balance was a venue issue, not a musicianship one, and it never once got in the way of the night.

The verdict

We chose this show over a group dinner, and I would make the same choice again without hesitating. A funny, energetic performer, a catalogue that runs from the Commodores to today, a duet with an old friend on the screen, “Three Times a Lady” at the piano — and a room that never stopped being part of it.

Overall: a great evening. If Lionel Richie is playing anywhere near you, go. He has not been away. He has been waiting for you to notice.

Jean-Francois Amyot is an independent journalist and author of The Art of War Remastered.
The Proper Steps to Raise Money Legally: Counsel, Structure, Disclosure, Then Investors

0
The Proper Steps to Raise Money Legally: Counsel, Structure, Disclosure, Then Investors

Standfirst: Most fundraising mistakes are made before the first investor is ever approached — in the order of operations. Founders who start with promotion and work backwards to paperwork inherit problems that are expensive to unwind. The lawful sequence runs the other way: counsel first, structure second, disclosure third, and investors last.

The mistake is usually sequence, not intent

Ask a founder how a raise begins and the answer is almost always a person: an uncle, a former colleague, a customer who believes in the product. Ask how it ends, months later, and the answer is often a document problem — a promise made in a text message that never made it into the subscription agreement, a shareholder who was never recorded properly, a round described one way in the pitch deck and another way in the filing.

Securities law is, in large part, a law about sequence. In the United States, an offer or sale of securities must either be registered with the Securities and Exchange Commission (SEC) or fit within an exemption from registration. That choice has to be made before the offering happens, because the exemption determines who may be approached, what may be said, what must be disclosed, and what must be filed. An exemption claimed after the fact, for an offering that was run a different way, is not a plan. It is an argument — and arguments with regulators are the most expensive way to finance a company.

The steps below are not a shortcut around that work. They are the work, in the order that makes each later step cheaper and safer than the one before it.

Step one: counsel before conversations

The first call in a lawful raise is not to an investor. It is to qualified securities counsel in every jurisdiction where the company is organised and where investors will be approached — in the United States, that means federal law and, depending on the path chosen, state law as well; in Canada, it means the provincial regulator in each province involved, such as Quebec’s Autorité des marchés financiers (AMF) or the Ontario Securities Commission.

Counsel’s first job is the threshold question covered in an earlier article in this series: is what the company plans to sell a security? Shares plainly are. So, very often, are notes, convertible instruments, and arrangements in which people put in money expecting a return from someone else’s efforts. If the answer is yes — and founders should assume it is until counsel says otherwise — then every later conversation happens inside securities law, whether the founder uses that vocabulary or not.

Counsel also tests eligibility before enthusiasm builds. Not every company can use every exemption, and not every investor can be included in every offering. Finding that out in week one is a planning problem. Finding it out after money has been accepted is a rescission problem, in which investors may have the right to demand their money back.

Step two: choose the structure that fits the raise you actually have

Only once the threshold question is answered does it make sense to choose a route — and the route should be chosen for the raise the company actually has, not the raise it hopes to have.

A private placement under Regulation D is built for sales to a defined group, principally accredited investors, with disclosure and filing obligations that depend on the rule relied on. Regulation Crowdfunding — Reg CF — lets an eligible company raise up to $5 million in a 12-month period from the public, but only through a registered funding portal or broker-dealer, with a Form C filed with the SEC and limits on how much a non-accredited investor may invest. Regulation A goes larger in two tiers — up to $20 million under Tier 1 and up to $75 million under Tier 2 in a 12-month period — in exchange for an offering statement on Form 1-A that must be qualified by the SEC before sales, audited financial statements and ongoing reporting under Tier 2, and, under Tier 1, state review as well. A fully registered public offering sits at the top of that ladder, with the heaviest disclosure and reporting of all.

None of these routes is “the easy one.” Each trades reach for obligation: the wider the audience a founder wants, the more disclosure, filing and reporting the law asks for in return. Choosing the smallest route that honestly fits the amount, the audience and the company’s ability to keep reporting afterwards is not a lack of ambition. It is what makes the raise finishable.

Step three: build the disclosure before anyone is asked for money

Disclosure is the product an investor is actually buying into. Before a lawful offering opens, the company prepares the material an investor needs to decide: what the business does, what the money will be used for, what the risks are, who runs the company, what the financial statements show, and what rights the security being sold actually carries — dividends, votes, and what happens if the company is sold or wound up.

Two disciplines matter here. The first is completeness: a statement that is literally true can still mislead if it leaves out a material fact, and anti-fraud rules apply to exempt offerings just as they do to registered ones. The second is consistency: the pitch deck, the offering documents, the filings and anything said in meetings or online must tell the same story. Where they differ, the least favourable version is usually the one that gets read back later.

Financial disclosure deserves its own warning. The level required depends on the route — Reg CF ties the required financial statements to the size of the offering, and Reg A Tier 2 requires audited statements — but the direction is constant: the larger and more public the raise, the more independently checked the numbers must be. A company that cannot produce statements a reviewer can follow is not ready to ask the public for money, whatever exemption it prefers.

Step four: paper the raise properly

A handshake is not a closing. A lawful raise runs on documents that match the structure chosen in step two: a term sheet that states the real terms, subscription documents in which each investor confirms what they are buying and on what basis they qualify, and an up-to-date capitalisation table that records every share, option and convertible instrument already promised to anyone.

This is also where the mechanics are fixed in advance: how money moves, whether it is held in escrow until a minimum is reached where the route requires it, what identity and anti-money-laundering checks the intermediary or the company will run, and when an investor is actually a shareholder — at signing, at payment, or at closing. Ambiguity on any of those points is tolerable in a friendship. In a shareholder register, it compounds.

Step five: communicate inside the rules of the route

Promotion is where well-prepared raises most often go wrong, because promotion feels like marketing and is treated by the law as part of the offering. Each route has its own communications rules: what may be said before a filing, what may be said while an offering is open, and what must be included when it is said. “Testing the waters” is permitted in some routes, under conditions — it is not a general permission to build demand however a founder likes.

The standing rules are simpler than the route-by-route detail. Never promise returns, a listing, or liquidity that does not exist. Never let urgency substitute for disclosure. And if anyone is paid, in cash or in shares, to talk about the offering or the company’s securities, that compensation must be disclosed in the promotion itself. Undisclosed paid promotion is not aggressive marketing; it is one of the clearest lines in securities law, and it is crossed in private, in writing, long before a regulator reads it.

Step six: close cleanly — then keep the obligations

Closing is an administrative act, and it should feel like one: documents signed, funds received through the channel the route requires, securities issued, and the register updated so that the company’s own record of who owns what is complete the day the money arrives. Under Reg CF, securities generally cannot be resold for one year; other routes carry their own resale limits, and investors should be told theirs in plain language before they invest, not after.

And closing is not the end. Reg CF issuers owe annual reports. Reg A Tier 2 issuers owe ongoing periodic reporting. Private issuers owe their investors the honest updates they promised, and every issuer owes the market consistency: material information shared fairly, not whispered to the investors most likely to complain. The founders who treat the raise as the start of a reporting relationship, rather than the end of a sales campaign, are the ones whose second raise is easier than their first.

The sequence is the strategy

Counsel, structure, disclosure, paper, controlled communication, clean closing, continuing obligations. None of those steps requires a large company or a large budget to begin — they require only that a founder refuse to run them in reverse. Money raised in the right order can be defended to an investor, a bank, an acquirer and a regulator with the same file. Money raised in the wrong order has to be explained four different ways, and the explanations rarely match.

That, in the end, is the practical case for doing it properly: not fear of a regulator, but the value of a record that never has to be rewritten.

This article is education, not legal or investment advice. Which exemption fits a particular company, what disclosure it requires, and how its offering may be communicated turn on the company’s specific facts and on the rules in force when the offering is made. Founders should take their own structure to qualified securities counsel before approaching any investor.

Jean-Francois Amyot is an independent journalist and author of The Art of War Remastered.
SEC and CFTC Nominations: Four Picks, Two Committees, One Fast Clock

0

President Trump has sent the Senate four nominees to fill long-empty seats at the Securities and Exchange Commission and the Commodity Futures Trading Commission — the two agencies at the centre of U.S. digital-asset oversight. The Senate Banking Committee booked the SEC pair for a hearing on November 19, within hours. The calendar, not the candidates, is the story.

What was announced

On November 12, 2026, the White House sent four nominations to the Senate — the first nominations to either agency in about a year, according to CoinDesk’s reporting:

— SEC: Steven Levine, a Republican — an attorney who has served as a senior lawyer at the Department of Labor and was Commissioner Mark Uyeda’s deputy chief of staff — nominated for a term ending June 5, 2030.

— SEC: Kristin Johnson, a Democrat — a former CFTC commissioner, now a professor at George Washington University School of Law — nominated for a term ending June 5, 2029.

— CFTC: Nathan Anonick, a Republican staffer for the Senate Agriculture Committee, nominated for a term ending June 19, 2031.

— CFTC: Matthew Rowland, a Democrat who served on Johnson’s CFTC staff, nominated for the remainder of a term ending April 13, 2028.

The pairing is deliberate: each agency gets one Republican and one Democrat, reflecting the bipartisan structure of both commissions.

The race against January 3

Within hours of the announcement, the Senate Banking Committee updated its calendar to hear the two SEC nominees on November 19. The Senate Agriculture Committee, which must clear the CFTC pair, has not yet scheduled its hearing, though Chairman John Boozman said he welcomes the nominations and looks forward to holding one soon, as reported by CoinDesk.

The urgency has a hard edge. The Senate is in a lame-duck session following the November 3 midterms, and nominations still pending when the current Congress ends on January 3 are returned to the President. Confirming four commissioners — two committee processes, then full Senate votes — in the remaining weeks is possible, but only if the committees move at the pace Banking set this week.

Why it matters for crypto

Both agencies have been operating short-handed while digital-asset policy is being written. The SEC and CFTC divide oversight of crypto markets between them — securities on one side, derivatives and much of spot-market structure on the other — and vacant seats affect everything from rulemaking votes to enforcement priorities. A Kristin Johnson confirmation would also put a former CFTC commissioner inside the SEC, an unusually direct bridge between the two regulators at the moment their jurisdictions over digital assets are being sorted out.

None of that is decided this week. What the November 19 hearing will show is whether the Senate intends to seat these commissioners in this Congress or leave the seats — and the policy that waits on them — to the next one.

Sources: CoinDesk policy reporting, November 12–13, 2026 — “U.S. President names CFTC, SEC nominees for first time in a year” (https://www.coindesk.com/policy/2026/11/12/u-s-president-names-cftc-sec-nominees-for-first-time-in-a-year); “U.S. Senate Banking Committee races toward hearing on new SEC nominations” (https://www.coindesk.com/policy/2026/11/13/u-s-senate-banking-committee-races-toward-hearing-on-new-sec-nominations); White House, “Nominations Sent to the Senate,” November 12, 2026 (names and terms as reported).

Jean-Francois Amyot is an independent journalist and author of The Art of War Remastered.
OSC Enforcement: Capital Markets Tribunal Schedules November 17 Case Management Hearing in the Freeman Case

0

Ontario’s Capital Markets Tribunal has scheduled a case management hearing in Ontario Securities Commission v Freeman, File No. 2026-7, for November 17, 2026. The notice is scheduling only — it makes no findings and imposes no sanctions.

What the Tribunal announced

On November 11, 2026, the Capital Markets Tribunal issued a notice in Ontario Securities Commission v Freeman, File No. 2026-7, stating that it has scheduled a case management hearing in the proceeding for November 17, 2026, at 10:00 a.m. The hearing will take place by videoconference.

The notice, signed by the Registrar of the Capital Markets Tribunal, states that members of the public may observe the hearing by videoconference by selecting the “View by Zoom” link on the Tribunal’s hearing schedule.

The November 11 notice does not set out the allegations in the proceeding, and this article does not summarize them. It contains no order and no reasons for decision.

Status and what happens next

This is a scheduling notice only. It is not a merits decision: the Tribunal made no findings in the notice, imposed no sanctions, and recorded no admissions. The proceeding remains pending, with the next step being the case management hearing on November 17, 2026, at 10:00 a.m. by videoconference.

Source: Capital Markets Tribunal, “Notice: Ontario Securities Commission v Freeman, File No. 2026-7,” November 11, 2026 — https://www.capitalmarketstribunal.ca/en/notices/notice-ontario-securities-commission-v-freeman-file-no-2026-7-3

Announcement date: November 11, 2026

Jean-Francois Amyot is an independent journalist and author of The Art of War Remastered.
Bitcoin at $68,000: What a Six-Week Slide Actually Shows

0

Bitcoin fell to about $68,000 overnight, its lowest level since August and its sixth straight weekly decline. The drop says less about bitcoin itself than about how quickly capital moves when a bigger story competes for it — this week, a record-setting stock offering and a strengthening U.S. dollar.

What happened

Bitcoin sank to roughly $68,000 overnight on November 12–13, trading below $70,000 for the first time since August, according to CoinDesk’s market reporting. The move extends a slide of more than 20% since early October. By CoinDesk’s count, bitcoin is down about 11% in November, 17% in the fourth quarter and 21% so far in 2026, and is on course for a sixth consecutive weekly loss — a streak last matched in the first quarter of this year, when prices bottomed near $60,000.

The selling was not gentle. CoinDesk reported that liquidations across crypto markets topped $1.6 billion as bitcoin hit its 12-week low, and U.S. spot bitcoin ETFs recorded continued outflows, including a large withdrawal from BlackRock’s IBIT fund.

The forces behind it, as reported

Analysts cited by CoinDesk pointed to several pressures arriving at once rather than a single cause:

— A stronger dollar and rate expectations. The U.S. Dollar Index hit a 19-month high as expectations grew that the Federal Reserve could raise rates at its December 9 meeting — conditions that historically weigh on risk assets priced in dollars.

— Competition for capital from the Anthropic IPO. The artificial intelligence company is seeking to raise as much as $64.4 billion in a Nasdaq listing expected around November 19, alongside a $26 billion private placement, and Bloomberg reported demand at roughly six times the shares available. Seamus Rocca, CEO of Xapo Bank, told CoinDesk that investors appeared to be selling liquid assets, including bitcoin, to free up cash for allocations.

— Turmoil in the AI trade itself, including upheaval at Nvidia, which CoinDesk said weighed on broader market sentiment, though analysts saw no direct link between Nvidia and bitcoin’s decline.

— Positioning: rising short positions and questions about Strategy’s place in MSCI indexes were also cited as adding pressure.

A pattern worth knowing

CoinDesk noted a recent parallel: ahead of SpaceX’s public debut in June, bitcoin fell roughly 20% in the days before the listing and rebounded toward its prior range after the offering launched. That is a pattern from one prior event, not a prediction — but it illustrates the mechanism at work. When a very large, heavily oversubscribed offering opens its books, short-term capital leaves liquid markets to chase allocations, and bitcoin, which trades around the clock, is often the first place that cash is raised.

What it does and does not mean

A six-week decline driven by dollar strength, rate expectations and a competing record IPO is a liquidity story. Nothing in this week’s reporting indicated a failure of the bitcoin network, a regulatory action against it, or a change in its supply rules — the three things that would alter its long-term structure. What changed is the price investors are willing to pay for it this week, in a market where leveraged positions amplified the move, as the scale of liquidations shows.

For readers, the practical lesson is the oldest one in markets: an asset that can be sold in seconds will be sold in seconds when cash is needed elsewhere. That is a feature of liquidity, not a verdict on the asset.

Sources: CoinDesk market reporting, November 13, 2026 — “Bitcoin plunges to $68,000 as Anthropic IPO frenzy adds to market jitters” (https://www.coindesk.com/markets/2026/11/13/bitcoin-slides-to-usd68k-as-nvidia-turmoil-anthropic-ipo-fuel-broader-market-sell-off); “Bitcoin’s six-week slide draws parallels with sell-off before SpaceX IPO” (https://www.coindesk.com/markets/2026/11/13/bitcoin-heads-for-sixth-weekly-loss-as-anthropic-s-blockbuster-ipo-looms). Prices and figures are as reported by those sources on November 13, 2026.

Jean-Francois Amyot is an independent journalist and author of The Art of War Remastered.
SEC Enforcement: SEC Charges Law Firm Employee Chetram Balli Alleging Repeated Insider Trading

0

The U.S. Securities and Exchange Commission has charged Chetram Balli, an employee of a large international law firm, alleging he repeatedly traded on material nonpublic information about forthcoming mergers and acquisitions involving the firm’s clients. The complaint seeks injunctive relief, disgorgement with prejudgment interest, and civil monetary penalties. The allegations are unproven and the litigation is pending.

What the SEC announced

In Litigation Release No. 26685, dated November 12, 2026, the SEC announced that on November 12, 2026, it charged Chetram Balli, an employee of a large international law firm, for allegedly using material nonpublic information to trade the stocks of the law firm’s clients and other entities involved in upcoming transactions.

The case is Securities and Exchange Commission v. Balli, No. 26-cv-7294 (E.D.N.Y.), filed November 12, 2026, in the United States District Court for the Eastern District of New York.

What the SEC’s complaint alleged

The conduct described below is what the SEC alleged in its complaint, as summarized in the release. Those allegations are unproven.

According to the complaint, Balli is employed as a document processing specialist at the New York office of a large international law firm with a substantial mergers and acquisitions practice. Through his employment, Balli allegedly obtained material nonpublic information about forthcoming announcements of mergers and acquisitions involving the law firm’s clients.

The complaint alleged that, between May 2025 and October 2026, despite his employer’s prohibition on engaging in insider trading, Balli traded on the basis of material nonpublic information on at least eight occasions and generated approximately $55,000 in ill-gotten profits.

The charges and relief sought

The SEC’s complaint charges Balli with violating the antifraud provisions of Section 10(b) of the Securities Exchange Act of 1934 and Rule 10b-5 thereunder.

The complaint seeks injunctive relief, disgorgement with prejudgment interest, and civil monetary penalties. No settlement, judgment, or finding is announced in the release.

Parallel criminal action and investigation

According to the release, on November 12, 2026, Balli was charged in a parallel criminal action brought by the U.S. Attorney’s Office for the Eastern District of New York. The release does not describe the outcome of that criminal action.

The SEC said its investigation originated with the Enforcement Division’s Market Abuse Unit, which used Consolidated Audit Trail (CAT) data to analyze Balli’s suspicious trading activity. The investigation was conducted by David C. Austin, John S. Rymas and Assunta Vivolo of the Market Abuse Unit and supervised by Market Abuse Unit Chief Joseph G. Sansone. The SEC’s litigation will be led by Mr. Austin, Ms. Vivolo and Todd Brody. The SEC said it appreciates the assistance of the U.S. Attorney’s Office for the Eastern District of New York, the FBI, and the Financial Industry Regulatory Authority.

Status and what happens next

As to Balli in the SEC action, a complaint has been filed and the litigation is pending. The allegations in the complaint remain unproven unless and until they are established in the proceeding or resolved by a settlement or judgment.

Source: U.S. Securities and Exchange Commission, Litigation Release No. 26685, Securities and Exchange Commission v. Balli, No. 26-cv-7294 (E.D.N.Y.) — https://www.sec.gov/enforcement-litigation/litigation-releases/lr-26685

Announcement date: November 12, 2026

Jean-Francois Amyot is an independent journalist and author of The Art of War Remastered.
SEC Enforcement: Final Consent Judgment for Jun Zhen in Alleged $2.2 Million Insider Trading Case, SEC Says

0

The U.S. Securities and Exchange Commission has announced a final consent judgment against Jun Zhen in a case alleging insider trading based on information obtained through work on clients’ EDGAR filings. The judgment reimposes a permanent injunction and orders $500,619 in disgorgement plus $8,832 in prejudgment interest, with payment deemed satisfied by a forfeiture order in a parallel criminal case.

What the SEC announced

In Litigation Release No. 26684, dated November 12, 2026, the SEC announced that on November 9, 2026, the United States District Court for the Eastern District of New York entered a final consent judgment as to defendant Jun Zhen in connection with his role in an alleged insider trading scheme. The case is Securities and Exchange Commission v. Chen et al., No. 25-cv-4580 (E.D.N.Y.), filed on August 18, 2025.

The release describes the judgment as a consent judgment. It does not state that Zhen admitted the allegations in the SEC’s complaint.

What the SEC’s complaint alleged

The conduct described below is what the SEC alleged in its complaint, as summarized in the release. Those allegations are unproven in the SEC action except as resolved by the consent judgment described in this article.

According to the complaint, Zhen and another individual were employed by a company that assisted its clients with making public filings in the SEC’s EDGAR system. Through that employment, Zhen and his colleague allegedly obtained material nonpublic information about clients’ forthcoming announcements of important events, including mergers and earnings results.

The complaint alleged that from around January 2025 to June 2025, despite their employer’s prohibition on engaging in insider trading, Zhen and his colleague traded on the basis of material nonpublic information on at least 13 occasions and generated more than $2.2 million in ill-gotten profits.

The relief the court ordered

On March 26, 2026, the court had entered a partial consent judgment against Zhen permanently enjoining him from violating the antifraud provisions of Sections 10(b) and 14(e) of the Securities Exchange Act of 1934 and Rules 10b-5 and 14e-3 thereunder.

The final judgment entered on November 9, 2026, reimposed that injunctive relief and ordered Zhen liable for disgorgement of $500,619 and prejudgment interest of $8,832. According to the release, payment of those amounts is deemed satisfied by the order of forfeiture entered against him in the parallel criminal action, United States v. Chen and Zhen, 25 cr. 303 (E.D.N.Y.).

Status and what happens next

As to Zhen in the SEC action, the final consent judgment has been entered. The release announces no further hearings or next steps as to him.

The SEC said its investigation originated with the Enforcement Division’s Market Abuse Unit, which used Consolidated Audit Trail (CAT) data to analyze Zhen’s and his colleague’s suspicious trading activity. The investigation was conducted by David Bennett, John S. Rymas and Lindsay S. Moilanen of the Market Abuse Unit and supervised by Market Abuse Unit Chief Joseph G. Sansone. The litigation was led by Ms. Moilanen and supervised by Christopher Colorado of the SEC’s New York Regional Office. The SEC said it appreciates the assistance of the U.S. Attorney’s Office for the Eastern District of New York and the FBI.

Source: U.S. Securities and Exchange Commission, Litigation Release No. 26684, Securities and Exchange Commission v. Chen et al., No. 25-cv-4580 (E.D.N.Y.) — https://www.sec.gov/enforcement-litigation/litigation-releases/lr-26684

Announcement date: November 12, 2026

Jean-Francois Amyot is an independent journalist and author of The Art of War Remastered.